Payactiv
- 46.64K
- 4.5
- Installs
- 1.00M
- Price
- Free
Screenshots
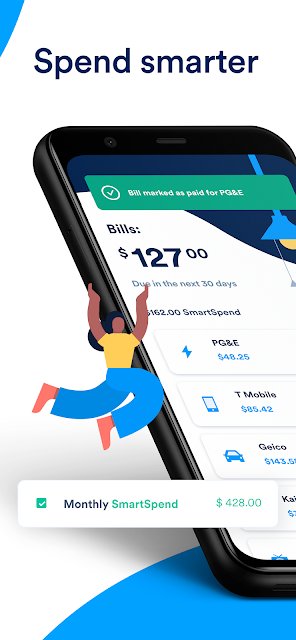
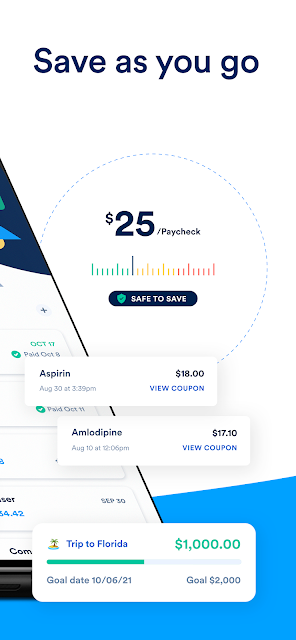
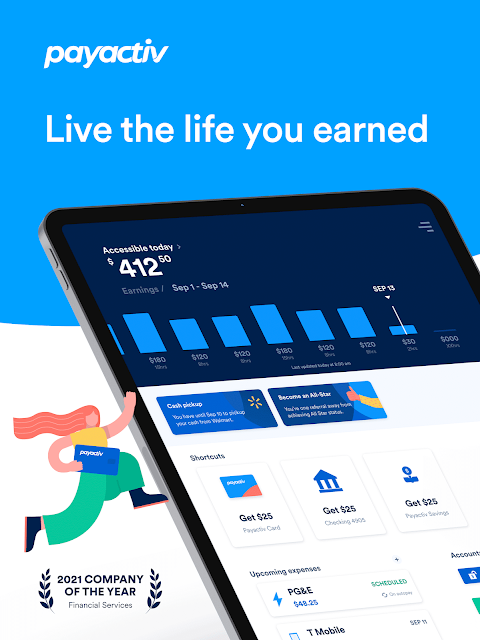
Analysis by Reviewed APKs
Payactiv is a finance app built around access to earned wages, along with tools for keeping an eye on spending and handling bills. It makes the most sense for people whose employers participate and who want more flexibility between paydays. I like the practical focus: it brings several everyday money tasks together, while making clear that access and timing depend on the deposit source and employer.
A Tighter Week Between Paydays
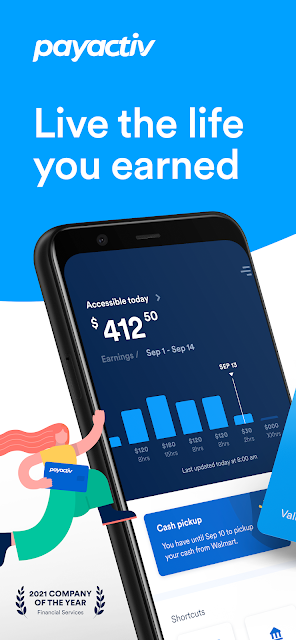
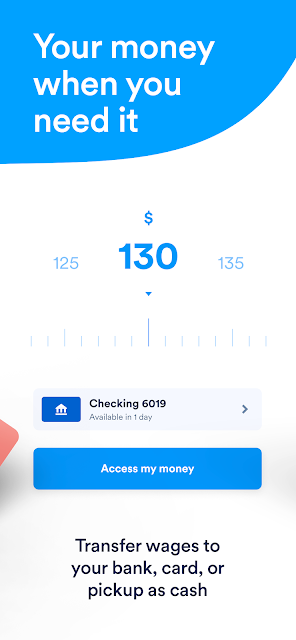
Picture a routine expense landing a few days before payday: a bill is due, or an unexpected cost has pushed the week’s budget off course. Payactiv is designed to help eligible users access wages they have already earned, rather than borrow against future income. I’d open it to see what funds are available, check the spending information, and decide whether using some of that pay now makes sense for the next few days.
The useful part is not just earlier access. Payactiv also describes low-balance alerts, spending tracking, automatic transfers, and bill pay through its card offering. In a busy week, those tools can make it easier to see what is happening before a payment is due. I would treat the app as a way to manage cash flow, not as extra income; drawing wages forward can leave less available when the regular payday arrives.
A Benefit, Not a Bank Replacement
Compared with a standard banking app, Payactiv puts earned-wage access near the center of the experience. It also brings in spending and saving tools and a Payactiv Visa Prepaid Card option. That combination may suit someone whose employer participates and who wants to connect pay timing with day-to-day expenses. It is a different proposition from an app focused only on balances, transfers, or broad financial planning.
I would not approach it as a payday loan, a general investing service, or a substitute for every feature of a full bank account. The description ties wage access to employer participation and says early deposit timing depends on the originator. Card terms and fees also apply, so the card’s details deserve a separate look. If your employer is not involved, the feature most distinctive to Payactiv may not be available to you.
Small Habits That Help
A good first habit is checking the app before a tight stretch of the month, rather than waiting until a payment is already late. Payactiv says it can show what is safe to spend and provide low-balance alerts. I’d use those cues alongside my own bills and account balances, then decide whether an early wage transfer is needed. The app’s view is useful context, not a reason to stop checking the rest of my finances.
The tracking and automatic-transfer options also make more sense as regular routines than as emergency buttons. A quick spending check once or twice a week can help me notice whether ordinary purchases are eating into money set aside for bills. If I use the card, I’d review its fee schedule and cardholder agreement before relying on a feature. That small bit of preparation helps keep convenience from turning into a surprise.
More From Our News Desk

Zoom Meetings, Google Meet, or Teams: Which Is Easiest to Join?

How I Build a Free Streaming Lineup With Tubi

Why Crunchyroll Is the Default Anime App for So Many Fans

YouTube TV: A Practical Guide to Cutting Cable

Rummikub and the Small Comfort of Phone Games

TeamViewer Remote Control or AnyDesk for Helping Family?
Who May Find It Useful
I’d recommend Payactiv to workers whose employers offer earned-wage access and who sometimes need more control over when they receive money they have already earned. It may also appeal to people who want spending visibility, low-balance alerts, bill pay, and a prepaid card in the same financial routine. The strongest fit is someone who will use those tools thoughtfully and keep track of how an early withdrawal affects the next payday.
It may be less compelling if your employer does not participate, if your pay already arrives when you need it, or if you want a comprehensive banking or investing app. Anyone considering the Payactiv Visa Prepaid Card should read its current terms and fees, since conditions apply. I also would not treat early access as a fix for a persistent gap between income and expenses; it changes timing, rather than creating additional earnings.
Payactiv is listed on Google Play under the developer name On-demand pay and beyond. The app has over 1 million installs and a 4.5-star rating from around 46,600 ratings. It is rated Everyone. Google Play lists version 2.2.11, with a release date of June 4, 2014, and a last update of October 26, 2026.
Payactiv is free to download, with no in-app purchases or ads shown in the supplied app facts. The minimum Android version is not included in those facts, so check Google Play for the requirement that applies to your device. The app’s wage-access and card services have eligibility, terms, and conditions of their own; free installation does not mean every related service is without fees.
How Payactiv Fits Into a Pay Cycle
A Straightforward First Look
When I first opened Payactiv, the central idea was easy to grasp: it connects access to earned wages with practical tools for managing money between paydays. That focus helps it feel less like a broad finance dashboard and more like a specific workplace benefit. The first thing I’d want to establish is whether my employer participates, because employer participation is required for earned-wage access.
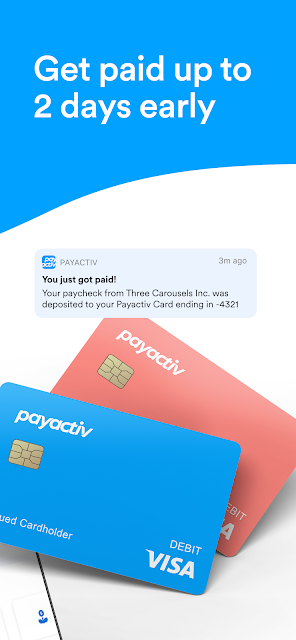
The app’s description also points to early access to some paycheck and government deposits, but those dates depend on when the originator sends a deposit. That makes expectations important from the start. I would use the app to understand the options available to me, rather than plan a bill around an arrival date that may depend on someone else’s processing.
The Everyday Money Check
The day-to-day appeal is having a place to review spending and see what Payactiv considers safe to spend. Low-balance alerts add another prompt to pay attention before a balance gets uncomfortably low. I can imagine checking those signals over morning coffee or before making a purchase, then comparing them with upcoming bills instead of relying on memory.
Automatic transfers from earned wages are another stated tool, alongside spending information at a glance. Together, these features encourage a more deliberate routine: know what is available, decide what needs to be set aside, and avoid treating every visible dollar as free to use. They are useful supports, but the description does not turn them into a complete budget or a substitute for personal judgment.
Card and Payment Options
The Payactiv Visa Prepaid Card is a notable part of the offering. Its described features include integrated bill pay, cash withdrawals at participating banks, and surcharge-free withdrawals at more than 37,000 MoneyPass ATMs. The card also has no minimum balance requirement, overdrafts, monthly fee, or inactivity fee according to the description. Those details are helpful to know, though the cardholder agreement and fee schedule remain the place to check the applicable terms.
Payactiv says the card can be used with Google Pay or Apple Wallet for touchless payments, and users can lock or replace a lost or stolen card. The description also mentions transfers between enrolled members without transfer fees, plus round-the-clock support in English and Spanish. These options make the card more flexible for daily use, but they are card-related services rather than reasons to assume every user has identical access.
A Weekly Paycheck Routine
A practical routine could start at the beginning of the week: check spending, note any bills coming due, and see whether a low-balance alert or other prompt calls for attention. If eligible, I’d consider early access only after working out how much of the next paycheck would remain. That simple pause matters, because receiving earned wages sooner also means having less of that same pay left for later.
Then I’d use the app’s tracking and automatic-transfer features as part of a repeatable plan, not just during a crisis. For instance, a regular check before the weekend could help me spot whether everyday spending is crowding out a bill. The aim is to make the timing of pay easier to manage, while keeping the bigger picture visible across the full pay cycle.
Important Boundaries
Payactiv’s most distinctive feature has a clear eligibility condition: earned-wage access requires employer participation. Early deposits also depend on the payment originator and when funds reach the card issuer. The app describes access to wages immediately in some cases and certain deposits early, but neither phrase should be read as a promise that every user or deposit will arrive on the same schedule.
The prepaid card has its own terms, conditions, and possible fees. The description directs cardholders to consult the cardholder agreement and fee schedule, and it notes that the card is issued by Central Bank of Kansas City. I would check those documents before choosing it for regular spending or withdrawals, rather than relying on a short feature summary.
Finally, early wage access is a timing tool, not a raise. It may help smooth a difficult week, but using it repeatedly can make later pay periods feel tighter. Payactiv’s spending information and alerts can help with awareness, yet the app works best when paired with a realistic view of bills and the next payday.
Payactiv has a clear purpose: help eligible workers access earned pay and manage the stretch between deposits with spending tools, alerts, and card options. I like that the description also makes room for practical tasks such as bill pay and transfers, rather than focusing on wage access alone. The main caveat is that participation and deposit timing depend on outside conditions.
I’d try Payactiv if my employer offered it and I wanted a more organized way to handle pay timing. I’d be more cautious if I needed dependable access on a particular date or expected it to replace a full-service bank. Before using the prepaid card, I’d review its current agreement and fees. For the right workplace setup, it looks like a useful cash-flow companion.
Payactiv Frequently Asked Questions
What is Payactiv used for?
Payactiv is a finance app for accessing earned wages when an employer participates, along with tools for tracking spending, getting low-balance alerts, setting automatic transfers, and using the Payactiv Visa Prepaid Card. It is intended to help manage money between paydays. Access and deposit timing depend on eligibility and the source of the payment.
Which devices support Payactiv?
Payactiv is available as an Android app through Google Play. The supplied app information does not give a minimum Android version, so check the Google Play store listing for the current device requirement. The description also says the Payactiv Visa Prepaid Card can be used with Google Pay or Apple Wallet; that does not mean the app itself is listed for both platforms.
What Android version does Payactiv require?
The minimum Android version for Payactiv can vary as the app changes and is worth checking on its Google Play store listing before installing. The app facts identify version 2.2.11, but that is the app version, not the Android operating-system requirement. Earned-wage access also requires employer participation.
Is Payactiv free, and are there fees?
The app is listed as free to download, with no in-app purchases or ads in the supplied app facts. The Payactiv Visa Prepaid Card has separate terms and conditions, and certain fees may apply. Review the current cardholder agreement and fee schedule for details; the app’s download price does not settle the cost of every service.
Is Payactiv a good fit for me?
Payactiv may suit you if your employer participates in earned-wage access and you want spending visibility or tools for managing the gap between paydays. It may not fit if you need access that is independent of your employer or want a general-purpose banking app. Eligibility, deposit timing, and card terms can vary, so check the store information and applicable service documents.
Pros
- Combines earned-wage access with spending tracking, low-balance alerts, and automatic transfers.
- Payactiv Visa Prepaid Card includes integrated bill pay and several withdrawal options.
- Describes wallet compatibility, card controls, and 24/7 support in English and Spanish.
- Free to download, with no ads or in-app purchases shown in the app facts.
Cons
- Earned-wage access requires employer participation.
- Early deposit timing depends on the payment originator and when funds are received.
- The prepaid card has separate terms and conditions, and certain fees may apply.
- Category
- Finance
- Version
- 2.2.11











