LemFi — Send. Save. Grow.
- 78.29K
- 4.9
- Installs
- 1.00M
- Price
- Free
Screenshots
Analysis by Reviewed APKs
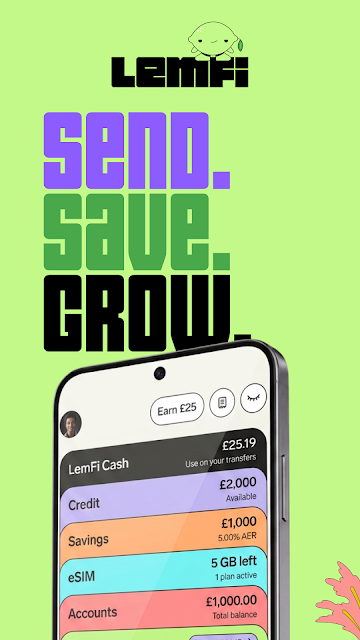
LemFi — Send. Save. Grow. brings international money transfers and travel eSIMs together, with savings and credit options for eligible customers in the UK. I see its clearest appeal for people who regularly support family abroad or travel between countries and want a few practical money tools in one app. Its range is useful, though which services you can use depends on your location and eligibility.
A transfer with fewer loose ends
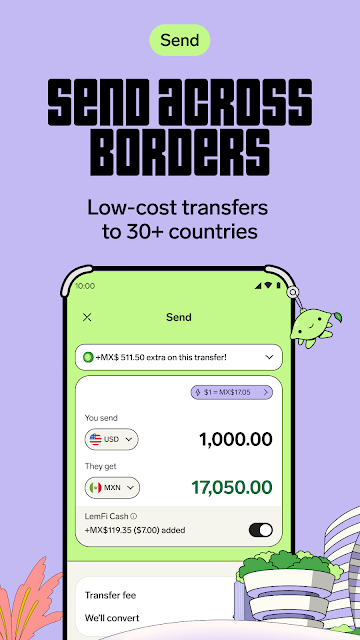
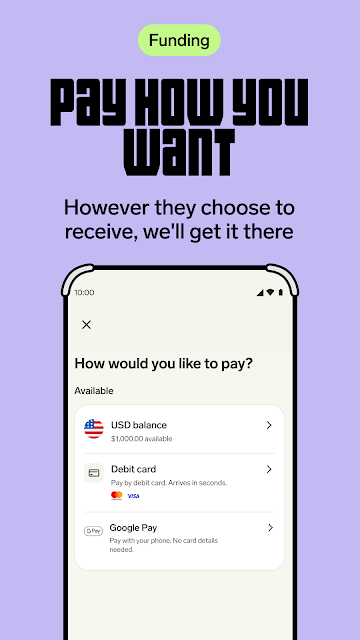
Imagine making a regular transfer home after payday. In LemFi, I can check the exchange rate and any fee before confirming, then follow the transfer while it makes its way to the recipient. Depending on the destination, the money can go to a bank account, mobile wallet, or mobile money account. That combination of up-front information and progress tracking makes the app’s central job easy to understand.
The service covers more than 30 countries across Africa, Asia, Europe, and Latin America, and some supported routes have zero transfer fees. Most transfers arrive in minutes, though the actual destination and delivery method matter. I like that LemFi describes what happens after I press send, rather than treating the transaction as finished the moment it leaves my screen. Arrival alerts can also help reduce the need to keep checking.
A specialist, not a full bank
Compared with a general banking app, LemFi is more focused on cross-border transfers, with travel data and some UK-only savings and credit options alongside them. For someone who sends money internationally and occasionally needs an eSIM, that mix can be more convenient than juggling separate services. It is also not a universal package: the available tools depend on where you live, and the UK savings and credit features have their own eligibility conditions.
I wouldn’t treat LemFi as a replacement for every financial service or assume every transfer route is free. In the UK, the LemFi account is an e-money account, not a bank account, and it is not FSCS protected. The savings account is a separate product provided by ClearBank, while credit is offered subject to status and affordability. Those distinctions matter more than the tidy all-in-one pitch.
Make a repeatable routine
A simple way to use LemFi is to check the recipient, destination, exchange rate, and fee before each transfer, then follow its progress until it lands. For a recurring family payment, I’d keep the routine consistent and use the arrival alert as a useful confirmation. The app supports delivery to different account types depending on the country, so I’d verify that the selected destination suits the person receiving the money.
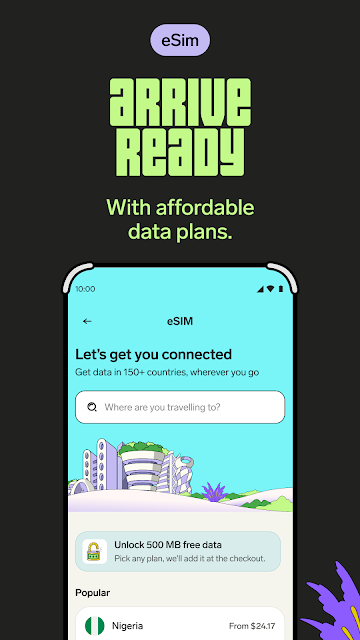
For a trip, the eSIM option is worth considering before departure rather than at the airport. LemFi offers data for more than 150 countries, so I’d check the destination and available data choices in the app while planning. UK customers using savings or credit can also keep those services in view, but I’d read their terms separately instead of assuming they work like the transfer feature.
More From Our News Desk

Zoom Meetings, Google Meet, or Teams: Which Is Easiest to Join?

How I Build a Free Streaming Lineup With Tubi

Why Crunchyroll Is the Default Anime App for So Many Fans

YouTube TV: A Practical Guide to Cutting Cable

Rummikub and the Small Comfort of Phone Games

TeamViewer Remote Control or AnyDesk for Helping Family?
Who may find it useful
I’d recommend LemFi to people who send money abroad regularly and want to see the rate, fee, and transfer progress in one place. It may also suit frequent travelers who like the idea of buying eSIM data before a trip. UK users who qualify for the savings or credit products may appreciate having those options in the same app, provided they understand that they are distinct services.
It may be a weaker fit if you only need a domestic banking app, or if your preferred country or payout method is not supported. People looking for budgeting tools should not choose LemFi on that basis: the supplied feature information centers on transfers, eSIMs, and UK savings and credit, not expense tracking. I’d also suggest checking eligibility and product details before relying on any particular feature.
LemFi — Send. Save. Grow. is developed by Pomelo Technology Inc. On Google Play, it has over 1 million installs and a 4.9-star rating from around 78,000 ratings. The app is free to download, with no in-app purchases or ads shown in its store details. Its content rating is Everyone.
The current version shown is 26.45.0. The app was released on October 3, 2020, and its listed last update was November 3, 2026. The Android version requirement is not included in the supplied app facts, so check Google Play for device compatibility. Transfer availability, fees, and eligibility for additional products depend on the route and service.
A closer look at LemFi’s everyday tools
A clear starting point
When I first open an app that handles money across borders, I want to understand what it actually does before I commit to anything. LemFi’s central proposition is straightforward: send money internationally, buy eSIM data, and, in the UK, access savings and credit if eligible. That makes the app’s intended audience fairly easy to identify, even though not every customer will have access to every service.
The most useful setup habit is to establish which feature applies to your situation. A transfer depends on the destination and payout method; UK savings and credit have separate conditions; and eSIM data is tied to travel destinations. I’d treat those as distinct jobs within one app, rather than assuming a single account feature unlocks everything. That practical distinction helps set expectations from the start.
Transfers in daily use
For a typical transfer, the important decisions happen before confirmation: where the money is going, how the recipient will receive it, and what exchange rate and fee apply. LemFi says it shows the exact rate and fee in advance. That gives me a concrete point to check before sending, rather than having to infer the cost from the amount that eventually arrives.
After sending, transfer tracking and arrival alerts are the details I’d value most in a routine. They offer a way to follow the payment from initiation through delivery, and most transfers are described as arriving in minutes. That is useful context, not a promise about every transaction. Destination, route, and payout type still shape the experience, so I’d leave room for variation.
Beyond sending money
The eSIM feature adds a travel use that fits naturally beside international transfers. LemFi lets users buy data for more than 150 countries in the app before traveling. I like the practical timing of that: sorting out connectivity before a flight can be simpler than looking for a local SIM after landing. The key is to check that the destination and data option meet the needs of the particular trip.
UK customers also have access to an Instant Access Savings account provided by ClearBank, with withdrawals available without penalty. The description says interest is calculated daily and paid monthly, and gives a boosted introductory rate followed by a tracker rate. Those rates can change, so I’d check current terms. The separate UK credit line and Credit Monitor are subject to eligibility; the latter offers eligible customers an Equifax score and information about what moves it.
A practical weekly rhythm
If I were using LemFi for family support, I’d make the transfer a deliberate weekly or monthly task. I’d confirm the recipient and payout route, inspect the rate and fee, and then use the tracking information rather than repeatedly asking the recipient whether the money has arrived. The arrival notification is a helpful end point for that routine, particularly when sender and recipient are in different time zones.
Before traveling, I’d check eSIM data as part of the same preparation session as reviewing the destination and trip dates. UK users with savings access could also use the app to put money aside and withdraw when needed, according to the product description. I’d keep credit decisions separate from travel planning, since the credit line is subject to status and affordability rather than being a simple add-on for everyone.
Limits to keep in mind
LemFi’s broad range can make it feel like a general financial hub, but its services have important boundaries. Transfers are available across more than 30 countries, not every country, and zero fees apply only to supported corridors. The payout options also vary by destination. I’d check the exact route and costs each time rather than assuming that a previous transfer tells me what a new one will cost.
The UK products need careful separation. LemFi says it is not a bank, and its e-money account is not FSCS protected. The savings account is provided by ClearBank and has its own deposit-protection terms; credit is provided by Pillar Labs and depends on status and affordability. These details do not make the app unsuitable, but they do mean the relevant product information deserves a read before use.
There is also a practical audience limit: some features are available only in the UK, and credit or savings eligibility may not apply to every user. Someone who wants budgeting, spending categorization, or a full set of domestic banking services may find that LemFi is not designed around those needs. Its strongest case is a more specific one: international transfers, travel data, and certain UK financial products.
LemFi makes the most sense when its core jobs match your routine. I like the combination of upfront transfer costs, progress tracking, arrival alerts, and travel eSIMs, with extra UK-only options for eligible customers. The app is focused enough to be useful, but its many services should not be mistaken for one universal banking product.
I’d suggest trying LemFi if you regularly send money across borders or want to arrange travel data in advance. Before using it for a particular transfer or financial product, check the route, current terms, and eligibility in the app. If you mainly need budgeting or everyday domestic banking, another app may be a closer fit.
LemFi Frequently Asked Questions
What is LemFi — Send. Save. Grow. used for?
LemFi is used to send money internationally and buy eSIM data for travel. In the UK, eligible customers can also access savings and credit products. Transfer availability and payout methods depend on the destination, while the savings and credit features have their own eligibility conditions.
Which devices can I use LemFi on?
LemFi is an Android app available through Google Play. The supplied app details do not give a minimum Android version, so check the Google Play page for current device requirements. The app description covers services in different countries, but feature availability can depend on where you are.
Does LemFi cost money, and are there in-app purchases?
The app is free to download on Google Play, and its store details show no in-app purchases or ads. Transfer fees depend on the corridor; the description says supported corridors can have zero transfer fees and that the rate and fee are shown before confirmation. Check the app for the current cost of your route.
What Android version does LemFi require?
The minimum Android version is not included in the supplied details. Check LemFi’s Google Play page on your device for the current compatibility requirement. The app’s version shown in the supplied facts is 26.45.0, but device compatibility is a separate question.
Is LemFi suitable for someone who only needs a bank app?
It may not be the closest fit if you only want everyday domestic banking or budgeting tools. LemFi focuses on international transfers and eSIM data, with savings and credit options for eligible UK customers. Its UK e-money account is not a bank account, and the savings and credit products are separate services.
Pros
- Shows the exchange rate and fee before confirming a transfer.
- Tracks transfers and offers alerts when money arrives.
- Combines international transfers with eSIM data for travel.
- UK savings and credit options add useful range for eligible customers.
Cons
- Transfer routes, payout methods, and fees vary by destination.
- Savings and credit are UK-specific and subject to eligibility.
- Its e-money account is not a bank account or FSCS-protected deposit.
- Category
- Finance
- Version
- 26.45.0











